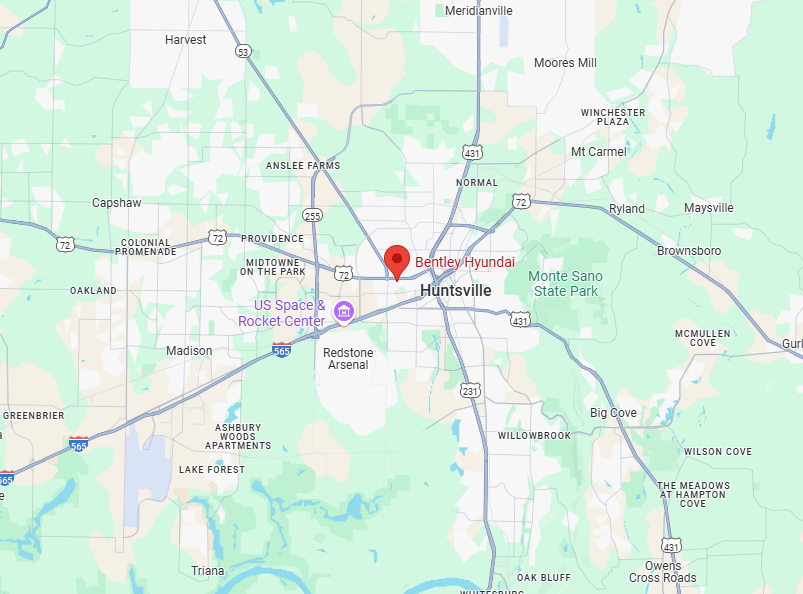


A PCS timeline, a growing family, or a daily commute to Redstone Arsenal can make replacing a vehicle feel urgent. This military auto financing guide is built to help active-duty service members, veterans, Guard and Reserve members, and military-connected shoppers make a confident decision without rushing the numbers. The right vehicle payment should support your current assignment and leave room for the changes military life can bring.
Start With the Full Vehicle Budget
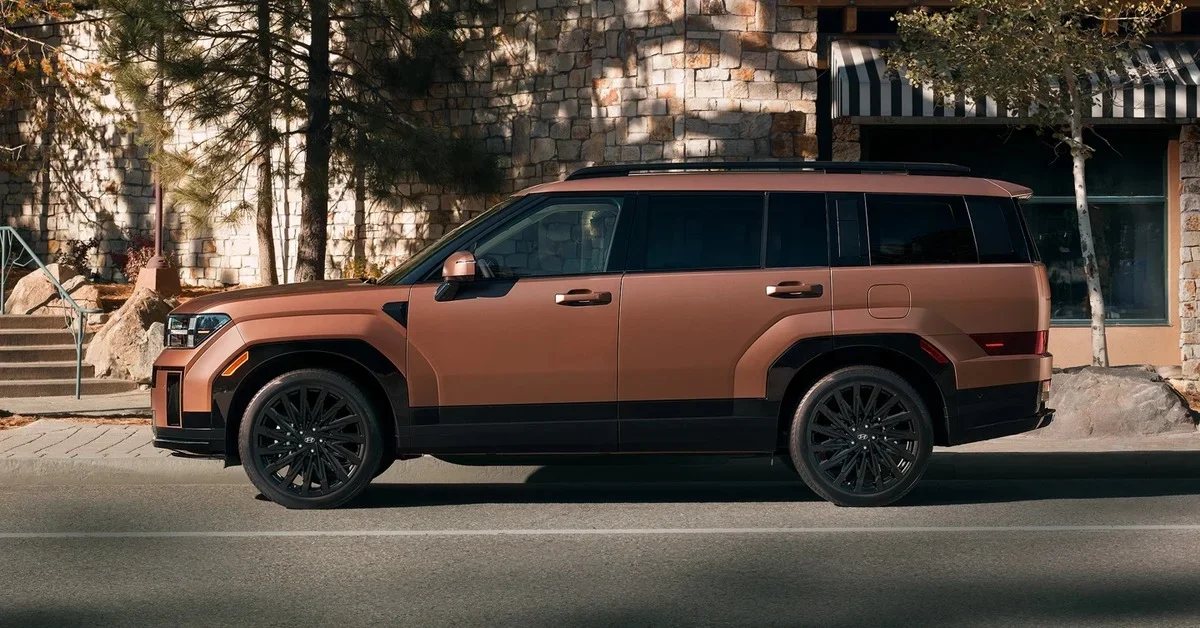
A monthly payment is easy to compare, but it is not the whole cost of ownership. Before applying for financing, decide what you can comfortably spend on the vehicle, insurance, fuel or charging, maintenance, and registration. That broader view matters whether you are shopping for a Tucson for everyday flexibility, a Palisade for family space, or an IONIQ model for an EV-focused commute.
Your down payment, trade-in value, loan term, interest rate, and vehicle price all affect the payment. Extending a loan term can lower the monthly amount, but it can also increase the total finance charge and may leave you owing more than the vehicle is worth for longer. A shorter term generally builds equity faster, provided the payment fits your household budget.
Build in breathing room. Deployment, a move, childcare changes, and unexpected repairs on another household vehicle can all shift your priorities. A payment that looks manageable only in a perfect month may not be the best fit.
Check Your Credit Before You Shop
Review your credit reports before you visit a dealership or submit finance applications. Look for incorrect balances, accounts that do not belong to you, or late payments reported in error. Addressing a mistake early can prevent confusion later when a lender reviews your application.
Credit is one factor in an approval decision, not a judgment of your financial discipline or service. Lenders also consider income, debt obligations, down payment, loan amount, and vehicle information. A limited credit history can still have financing paths, though the available terms may differ from those offered to an established borrower.
If you expect a change in pay because of an upcoming move, deployment, or end of a special allowance, work from your dependable base household income rather than temporary circumstances. Having a realistic number in mind makes it easier to evaluate an offer on its merits.
Compare Financing Sources, Not Just Payments
Military shoppers often start with a bank or credit union, and that can be a smart way to understand the rates and terms for which they may qualify. A preapproval gives you a useful benchmark, but it does not mean you should stop comparing options.
Dealership financing can provide access to multiple lending sources in one process, including manufacturer-related programs when available. The strongest option depends on your credit profile, the vehicle you choose, available incentives, your down payment, and the term you select. Ask for a clear explanation of the annual percentage rate, loan length, total amount financed, and payment before making a final decision.
A lower payment is not automatically a better deal. Compare offers using the same loan term and similar down payment whenever possible. If one proposal stretches the loan farther to reduce the payment, it is not a direct apples-to-apples comparison.
Questions Worth Asking Before You Sign
Ask whether there is a prepayment penalty, how the first payment date is set, and whether an automatic payment discount applies. If you are using a trade-in, confirm how its value and any remaining payoff are included in the transaction. You should also understand which products are optional and which charges are required by law or lender policy.
Take the paperwork seriously, but do not feel pressured to pretend you understand a term you do not recognize. A good finance conversation gives you time to ask direct questions and receive direct answers.
Have the Right Documents Ready
Coming prepared can make the financing process more efficient, especially if you are shopping around work schedules or approaching a move. Requirements vary by lender and applicant, but it helps to bring or have digital access to the following:
- A valid driver license and current contact information
- Proof of income, such as recent pay statements or other lender-accepted documents
- Proof of insurance or the information needed to obtain coverage
- Your trade-in title, registration, payoff details, and all keys if applicable
- Documentation for a co-buyer or co-signer, if you are applying with one
If your address on your license does not match your current residence because of military orders or a recent move, mention it early. A finance specialist can tell you what additional verification the lender may need.
Use Military Protections Wisely
Federal military consumer protections can be valuable, but they do not replace reading your contract. The Servicemembers Civil Relief Act may provide interest-rate protections for certain obligations incurred before active-duty service and may provide lease protections in qualifying deployment or PCS situations. Eligibility depends on the specific facts, timing, and type of contract.
Do not assume that every vehicle loan receives a special rate or that every lease can be ended without conditions. Keep copies of orders and financing paperwork, and speak with your installation legal assistance office if you need guidance about protections related to your circumstances. Clear records are especially helpful if your status changes after you purchase or lease a vehicle.
Decide Whether a Loan or Lease Fits Your Assignment
Buying and leasing solve different problems. With a purchase, you are working toward ownership and can drive as many miles as you choose, subject to vehicle condition and warranty coverage. That flexibility can be appealing for North Alabama families who take frequent road trips, commute across the region, or prefer to keep a vehicle for many years.
A lease may fit shoppers who want a newer vehicle at regular intervals and can stay within the mileage and wear guidelines. It can be worth considering for some EV-curious drivers who want to experience an IONIQ 5, IONIQ 6, or Kona Electric before committing to long-term ownership. Still, military travel can complicate mileage planning. Review the lease term, mileage allowance, wear standards, and options at the end of the agreement before choosing this route.
For either option, consider how long you expect to keep the vehicle, where it may be driven, and whether another assignment could change your needs. A compact Kona may be ideal for one stage of life, while a Santa Fe or Palisade may make more sense if passengers, cargo, or car seats are part of the daily routine.
Protect the Value of Your Trade-In
Your current vehicle can reduce the amount you need to finance, but only if you have a clear picture of its value and payoff. Gather the vehicle identification number, current mileage, service records, condition details, and loan payoff information before requesting an appraisal.
If you owe less than the trade-in is worth, the difference can contribute to your next purchase. If you owe more, that negative equity does not disappear. It may be rolled into the next loan, increasing the amount financed. Depending on the gap, it may be better to wait, make an additional payment, or choose a vehicle that keeps the overall financing plan comfortable.
Be candid about accident history, warning lights, and mechanical concerns. An accurate appraisal from the start protects you from surprises later in the process.
Review Insurance and Optional Coverage
Your lender will typically require full coverage insurance on a financed or leased vehicle. Get an insurance quote for the specific vehicle before finalizing your decision, particularly when comparing gas, hybrid, and electric models. Insurance costs can vary based on the vehicle, your driving history, location, and coverage choices.
Ask about guaranteed asset protection, commonly called GAP, if your down payment is small, your loan term is longer, or negative equity is part of the deal. GAP may help address a difference between an insurance settlement and the remaining loan balance after a qualifying total loss. It is not right for every buyer, and its terms matter. Review cost, cancellation options, and whether comparable coverage is already available through your insurer.
A Better Way to Finish Your Military Auto Financing Plan
Once you have compared the vehicle, loan or lease terms, insurance impact, and trade-in details, take one last look at the complete agreement. The goal is not simply to leave with keys. It is to leave with a vehicle that fits your life now and a financing plan you can carry with confidence through whatever comes next.
At Bentley Hyundai, military-connected shoppers can use online tools to explore inventory, value a trade, and get pre-approved before a visit. Then bring your questions to the dealership. A straightforward conversation and a careful review of your options can turn a time-sensitive vehicle decision into one you feel good about long after the paperwork is complete.
Frequently Asked Questions
Can I finance a car in Alabama if my orders will move me out of state?
Usually, yes. An auto loan generally follows you when you relocate, but you will need to update the registration, title, and insurance in your new state as required. Tell the lender and the finance team about upcoming orders so the paperwork, contact details, and first payment date fit your timeline.
Does Hyundai offer a military program for Redstone Arsenal personnel?
Hyundai has offered a military program for eligible active duty, Reserve, National Guard, veteran, and retired service members, with eligibility verification required. Program terms and availability change, so check Hyundai's current details and ask the Bentley Hyundai team whether a program can apply to the vehicle you choose. It may be combinable with some offers but not others.
What should I do with my car loan if I deploy from Huntsville?
Keep payments current, set up automatic payments if possible, and give a trusted person access to account information through an appropriate legal document. Store the vehicle safely and review insurance options with your insurer. The installation legal assistance office can explain whether any protections apply to your specific loan or lease before you leave.
Can I get pre-approved online before visiting Bentley Hyundai?
Yes. Bentley Hyundai has an online financing application you can complete before a visit, which helps when shift work or training schedules make dealership time limited. Pre-approval gives you a budget to shop within. Final terms still depend on the vehicle you select, your down payment, and the lender's review of your application.